Commercial Recovery: Moving Beyond the “Check is in the Mail”
You’ve sent the invoice. You’ve called Accounts Payable. You’ve been promised “the check is in the mail.” For a CFO, controller, or credit manager, that’s usually the signal to stop chasing and start escalating. Our Account Reconciliation Team bypasses the gatekeepers and gets your invoice in front of the person who actually approves payment, serving hundreds of businesses nationwide to resolve the billing gridlock that’s stalling your accounts receivable.
Quick answer: The earlier a delinquent B2B account moves to professional recovery, the higher the odds of getting paid. Accounts under 180 days past due recover at roughly 80%; that rate falls the longer an invoice sits, since a debtor’s cash, attention, and willingness to prioritize an aging vendor bill all decline with time. Commercial debt collection works best as a structured, early escalation, not a last resort after months of internal follow-up.
Our recovery rate runs over 75% for B2B accounts less than 250 days old, climbing to about 80% for accounts under 180 days. More than 90% of accounts resolve without ever filing suit. No Recovery = No Fee.
Protecting your business reputation, Collect911 holds licenses in all 50 states, ensuring a safe approach for every client interaction. We provide free litigation and bankruptcy scrubs with zero onboarding or annual fees. Our SOC 2 Type II ensure total data security, backed by a 4.85/5 rating from over 2,000 professional reviews. Delivering high recovery rates!
Need a Commercial Collection Agency? Contact us
In-House Follow-Up vs. Professional Commercial Recovery
| Metric | In-House A/R Follow-Up | Collect911 Commercial Recovery |
|---|---|---|
| Staff time required | Ongoing, competing with the rest of your finance team’s workload | Minimal — account is handed off, tracked through updates |
| Recovery probability (180+ days past due) | Declines sharply without dedicated leverage or tools | ~75–80% on accounts under 250 days |
| Commercial credit bureau reporting | Not typically available to an individual creditor | Available for eligible accounts, adds real pressure |
| Skip tracing & asset investigation | Limited to what staff can find manually | Litigation, bankruptcy, UCC, and address checks included |
| Legal escalation | Requires sourcing and vetting outside counsel separately | In-network attorney referral with pre-litigation analysis |
The Performance-Based Recovery Model
Our commercial strategy is results-driven with zero upfront risk to your firm. We operate on a Tiered Contingency model: no recovery, no fee. Fees range from 10% to 45% depending on the balance, age, and complexity of the account, communicated to you in advance for total transparency. This aligns our incentives with yours, applying 20+ years of commercial credit and recovery experience to resolve balances efficiently.

The Commercial Collection Roadmap: Our 8-Step Process
Out-of-court settlement is always our top priority. We use advanced negotiation, compliance-driven outreach, and credit reporting leverage to resolve delinquent accounts amicably. This approach recovers your money faster, protects professional relationships, and saves you hundreds in court costs and legal fees.
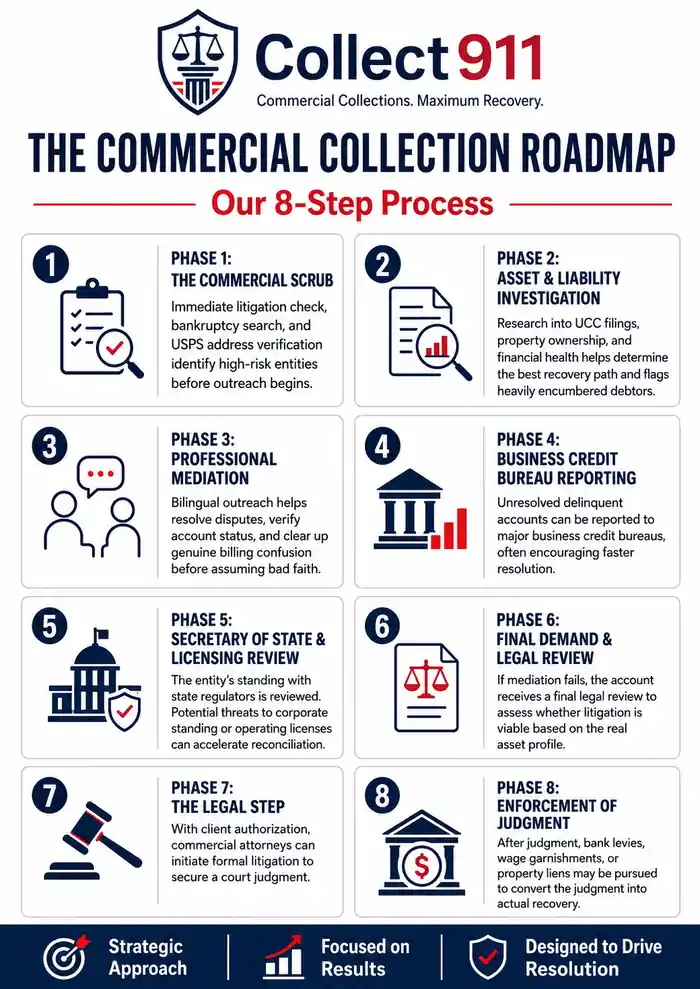
Phase 1: The Commercial Scrub
Every account undergoes an immediate litigation check, bankruptcy search, and USPS address verification to identify high-risk entities before any outreach begins.
Phase 2: Asset & Liability Investigation
Deep-dive research into the entity’s financial health, including UCC filings and property ownership, determines the most effective recovery path, and flags accounts where a debtor’s assets are already heavily encumbered elsewhere.
Phase 3: Professional Mediation
Bilingual outreach acts as a professional intermediary to resolve disputes and verify account status, aiming to clear up genuine billing confusion before assuming bad faith.
Phase 4: Business Credit Bureau Reporting
If an account remains unresolved, the delinquency can be reported to major business credit bureaus, impacting the entity’s ability to secure future credit and often prompting faster resolution.
Phase 5: Secretary of State & Licensing Review
The entity’s standing with state regulators is verified. Flagging potential threats to corporate standing or operating licenses often accelerates reconciliation.
Phase 6: Final Demand & Legal Review
If mediation fails, the account is escalated for a final legal review to determine whether litigation is viable given the entity’s actual asset profile, not just the size of the balance.
Phase 7: The Legal Step
With your authorization, our network of commercial attorneys initiates formal litigation as a final action to secure a court judgment.
Phase 8: Enforcement of Judgment
Post-judgment, bank levies, wage garnishments, or property liens are pursued where available to convert the judgment into an actual recovery.
Clinical Philosophy: Urgent, Effective, and Respectful
As an Account Reconciliation Team, we operate as an authoritative peer to your accounting department, not an outside collections operation. A late payment is often a breakdown in communication rather than a refusal to pay, so acting as mediators resolves discrepancies without damaging long-term vendor relationships. This frees your staff to focus on growth rather than the grind of chasing balances.
The Security & Integrity Suite
Integrity is non-negotiable. Every call is recorded and audited to protect professional standards and your reputation. A litigation check at intake identifies debtors with a documented history of using frivolous lawsuits to avoid paying, a real and growing tactic among sophisticated commercial debtors.
Realistic Smart Collection Methodology
A wholesale equipment distributor had a single commercial account, a regional contractor, fall 140 days past due on a $72,000 order of heavy machinery parts. Internal follow-up calls had gone unanswered for two months. An asset and liability check found the contractor was mid-bid on several new municipal contracts, giving real weight to a credit-bureau reporting threat, since a delinquency mark could jeopardize their bonding and bidding eligibility. Within three weeks of that leverage being applied, $65,400 of the balance was recovered through a negotiated payment plan, avoiding litigation entirely.
Here are two more recent B2B commercial debt recovery results:
Result 1: The Building Materials & Wholesale Distributor
-
The Situation: A regional building supplies distributor was owed $82,000 by a commercial subcontractor who had gone completely silent after completing a project. The invoice was 140 days past due, and the client’s internal accounts receivable team was receiving standard stall tactics (“we’re waiting on general contractor funding”).
-
The Solution: The distributor submitted the account to Collect911’s B2B commercial recovery program. The team immediately conducted corporate asset discovery and skip-tracing, identified active business operations, and issued a firm, compliant formal commercial demand notice.
-
The Result: Within 21 days, Collect911 negotiated a structured 2-part payment agreement. The full $82,000 balance was recovered in full, allowing the distributor to avoid writing off a massive margin-draining loss.
Result 2: The Industrial Equipment Rental & Logistics Firm
-
The Situation: An equipment rental firm was holding $45,500 in overdue balances across three separate commercial accounts ranging from 90 to 180 days past due. The debtor companies were ignoring direct staff emails and withholding payment while continuing operations elsewhere.
-
The Solution: The firm transferred the accounts to Collect911’s Performance Contingency commercial model. Collect911 initiated pre-litigation analysis and leverage via commercial credit bureau reporting options, signaling that the debts would directly impact the debtors’ corporate credit profiles.
-
The Result: Within 35 days, two debtors paid their balances in full, and the third entered a verified payment schedule. Collect911 recovered $39,800 (87.4%) of the total outstanding commercial debt without requiring costly courtroom litigation.
Frequently Asked Questions
What’s a typical contingency rate for B2B debt recovery, and why does it vary so much?
Rates generally run 10% to 45%, and the spread comes down to age, complexity, and dollar size rather than being arbitrary. A fresh, well-documented $50,000 invoice is a very different recovery project than a $3,000 balance that’s been stale for two years and needs skip tracing just to find a working address. The fee should track the actual work and risk involved in a specific account, not a flat number applied across the board.
Our delinquent customer is a franchisee. Can we pursue the franchisor for the unpaid balance?
Usually not, and it surprises a lot of suppliers. Franchise law generally treats a franchisee as an independent business responsible for its own trade debts, and a franchisor typically isn’t on the hook just because their name is on the sign outside. The exceptions are narrow: a franchisor that personally guaranteed the account, or one so operationally entangled with the location that a court treats it as the franchisee’s true employer or principal, which is a high bar. Knowing which entity actually signed your credit application matters more here than which brand is on the building.
The account that owes us is a government agency or municipality. Does that change how collection works?
Significantly. Government entities generally can’t be pursued the same way a private company can; sovereign or governmental immunity often blocks standard lawsuits and asset seizure, and many agencies have their own required claims process that has to be followed before a court will even hear the matter. Wage garnishment and bank levies, the usual post-judgment tools, frequently aren’t available against a public entity’s operating funds at all. These accounts almost always call for a different playbook than a private commercial debtor.
We just learned our invoice was already sold to a factoring company. Does that change who we’re actually owed by, or who can collect?
It can shift the account out of your hands entirely. Once a receivable is genuinely sold to a factor, the factor typically owns the right to collect it, not the original business, and their own factoring agreement usually dictates who pursues a nonpaying account and under what terms. Before assuming you can place that invoice with us directly, it’s worth confirming whether the sale was a true sale or a recourse arrangement where the obligation could come back to you.
Our research turned up a UCC-1 blanket lien from the debtor’s bank. Is the account still worth pursuing?
Often, yes, just with adjusted expectations rather than none at all. A blanket lien means a secured lender has first claim on the debtor’s assets in a liquidation or bankruptcy scenario, which affects what’s realistically recoverable if things go that far, but it doesn’t erase an ordinary business’s incentive to pay a routine trade invoice to keep operating and preserve vendor relationships outside of a worst-case scenario. This is exactly the kind of finding our Asset & Liability Investigation step is meant to surface early.
Could we get sued for harassment or an FDCPA-style violation while trying to collect a B2B debt ourselves?
It’s a real risk, more than most business owners assume. While the federal FDCPA is written around consumer debt, a number of states have their own statutes that extend similar communication and conduct restrictions to original creditors collecting commercial debt, and even outside those laws, a debtor pushed too hard has other legal theories, harassment, defamation, tortious interference, available if a collection effort gets aggressive or public. This is part of why moving a stalled account to a professional team is often the lower-risk path, not just the more effective one.
Areas of Commercial Expertise
- Commercial Lease & Property Management Arrears
- Manufacturing & Supply Chain Invoice Reconciliation
- Professional Services & Consulting Balances
- Wholesale & Distribution Account Recovery
- SaaS & Technology Subscription Arrears
- Construction & Subcontractor Payment Disputes
Ready to Clear Your A/R Ledger?
Don’t let unpaid invoices choke your cash flow. Let us apply the professional pressure needed to get you paid.